
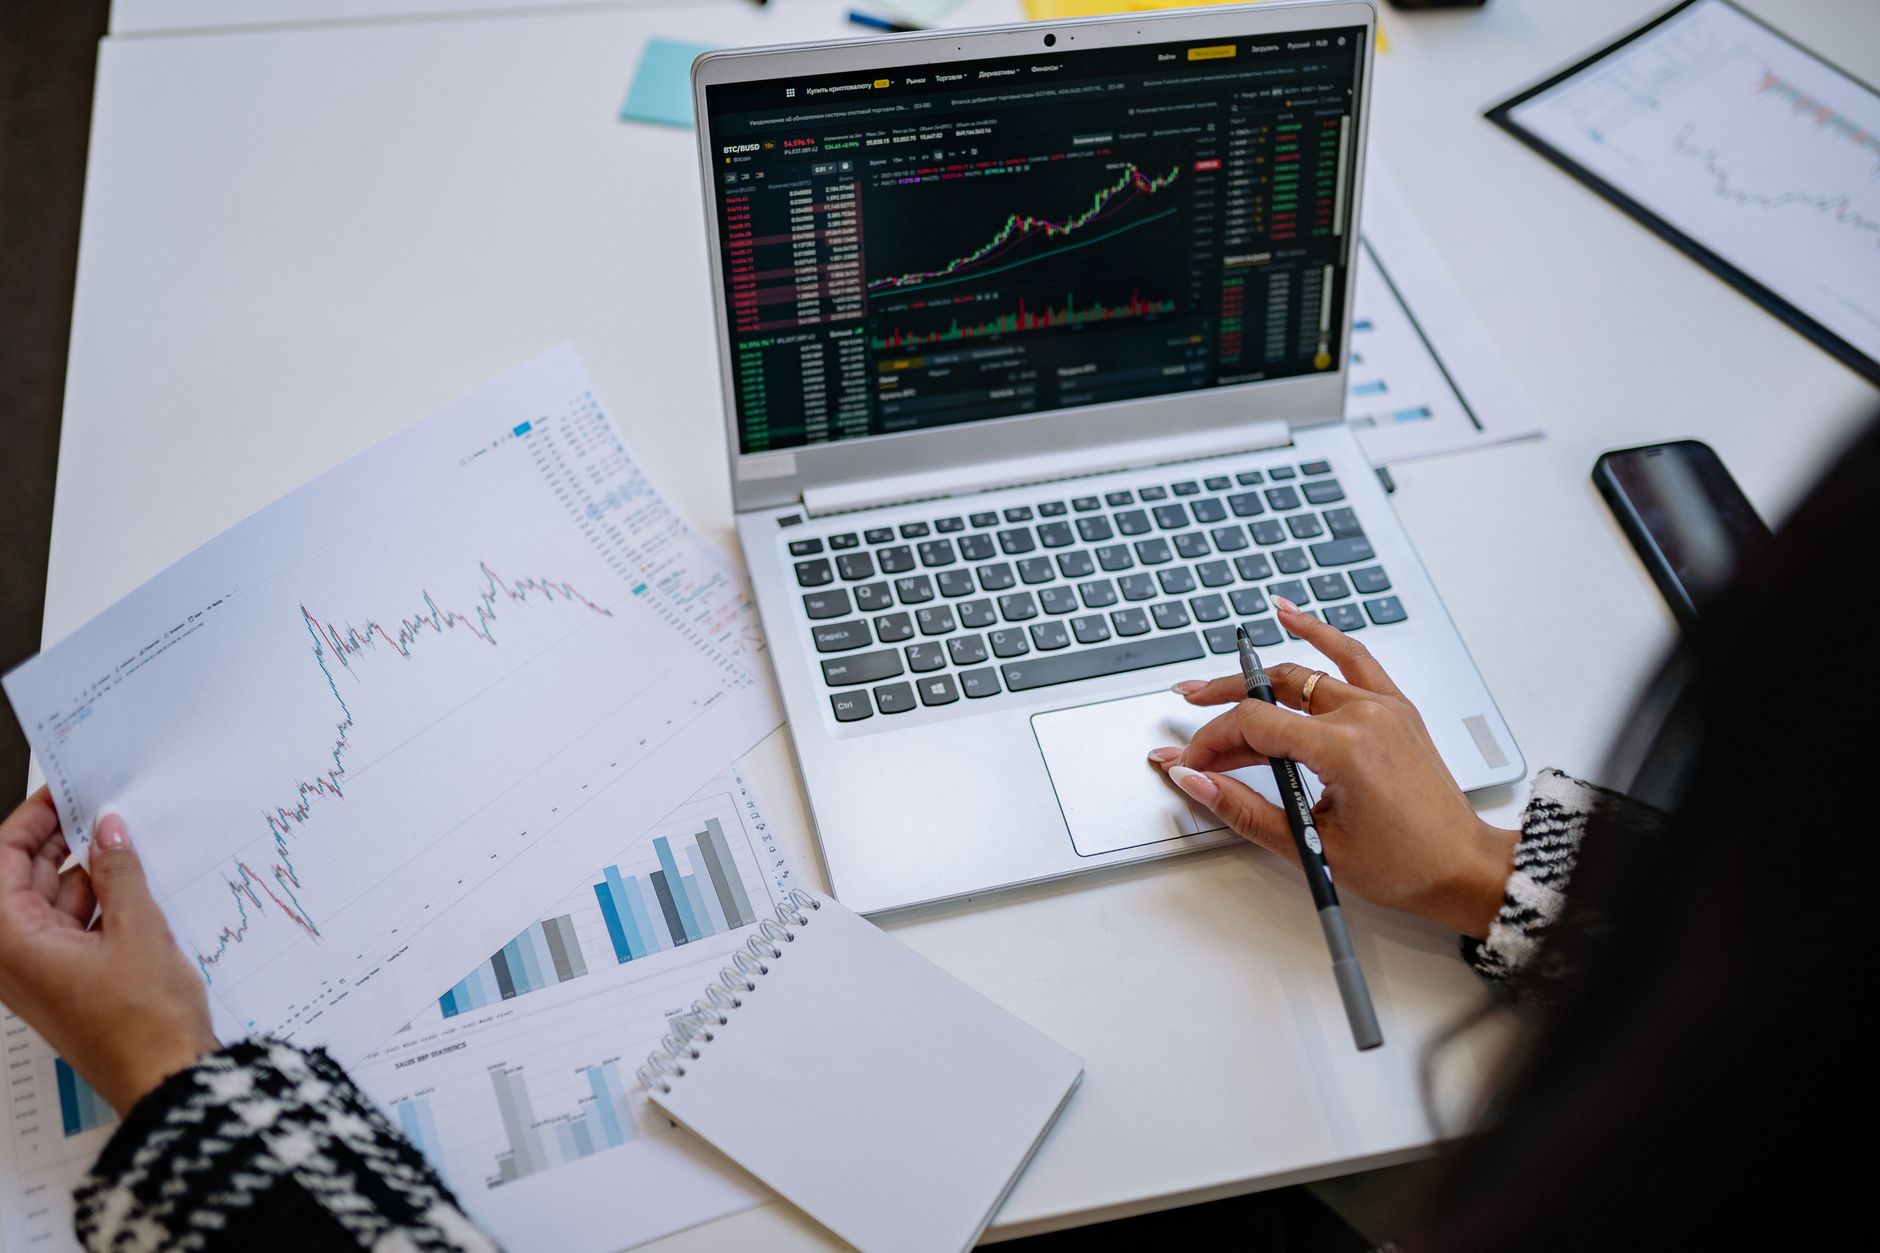
Wall Street is facing a stark valuation puzzle regarding Palantir Technologies, as analysts weigh unprecedented enterprise demand for its artificial intelligence platforms against lofty share prices. While commercial sector adoption of its Foundry and AIP platforms continues to accelerate at a remarkable pace, market experts remain sharply divided on whether current financial metrics justify the software maker's steep equity valuation.
The debate stems from Palantir's transition from a government-reliant defense contractor into a dominant commercial software player. Recent earnings reports highlight robust revenue expansion, particularly across North American enterprise accounts. Yet, traditional valuation models suggest the stock has priced in years of flawless future execution, leaving little margin for error if macroeconomic headwinds cause corporate clients to tighten IT budgets.
Institutional sentiment reflects this tug-of-war between growth potential and price discipline. Bullish analysts point to Palantir's unique market position and expanding operating margins as proof that standard software metrics fail to capture its true competitive moat. Conversely, bears argue that the risk-to-reward ratio has grown unfavorable following consecutive quarters of aggressive multiple expansion.
As enterprise spending patterns evolve through the remainder of the fiscal year, market participants will monitor whether Palantir can sustain its current momentum. Sustaining high-margin growth while expanding its commercial customer base will ultimately determine if the tech firm can grow into its ambitious market capitalization.
Wall Street Splits Over Palantir Valuation as Enterprise AI Growth Peaks


Comments