
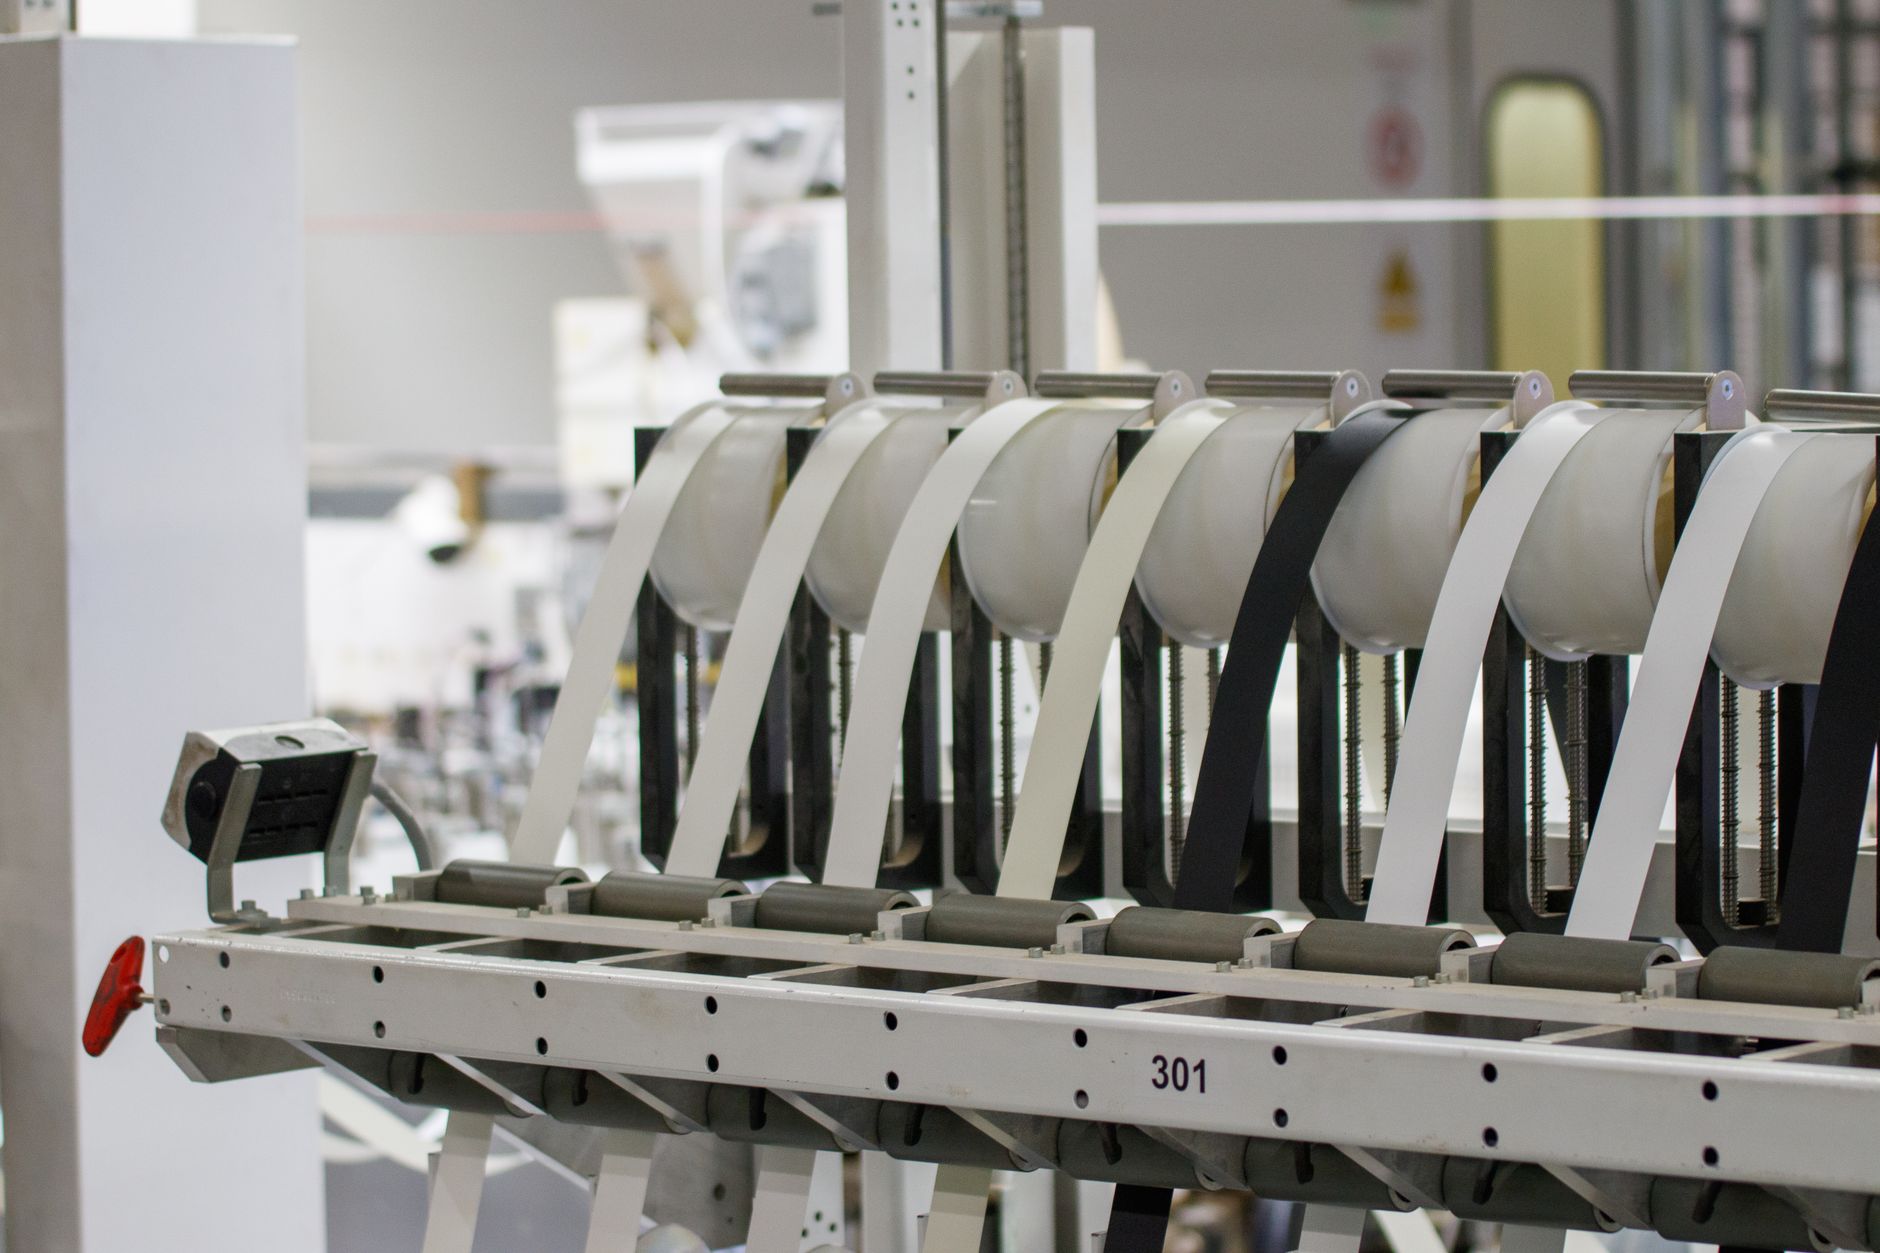
International technology conglomerates are grappling with a stark operational reality as hardware supply chains remain deeply anchored within Chinese manufacturing ecosystems. Despite multi-year efforts by Western governments to diversify sourcing and decouple sensitive tech production, recent industrial output data shows that global brands still depend heavily on specialized factories scattered across East Asia. Specialized components, rare earth processing, and advanced assembly lines have proven remarkably difficult to replicate elsewhere, leaving major corporations with limited viable alternatives for mass-market hardware deployment. This persistent reliance highlights a widening gap between geopolitical ambitions and the ground-level logistics of consumer electronics manufacturing.
The strategic leverage held by these industrial hubs stems from decades of concentrated infrastructure investment, highly skilled engineering talent pools, and deeply integrated supplier networks. When a consumer electronics giant or an enterprise hardware provider designs a new device, the path from prototype to scaled assembly almost invariably crosses through specialized facilities capable of producing millions of units under tight tolerances. Competitors attempting to establish parallel manufacturing ecosystems in Southeast Asia, India, or North America routinely encounter significant bottlenecks, ranging from regulatory hurdles to shortages of locally sourced sub-components. Consequently, cost structures and production timelines remain tied to the operational efficiency of established manufacturing corridors.
Industry analysts suggest that mitigating these supply chain dependencies will require sustained capital expenditure and unprecedented cross-border cooperation among allied nations over the next decade. Short-term fixes involving minor supplier shifts have done little to reduce systemic exposure to localized disruptions or policy changes. As hardware innovation accelerates—particularly in demanding sectors like high-performance computing, specialized semiconductors, and advanced robotics—the underlying manufacturing foundation remains the ultimate arbiter of who successfully scales new technology. Until alternative production clusters mature, global competitors will continue operating in a landscape where accessing world-class hardware means working on terms dictated by the world's most dominant manufacturing base.
China's Manufacturing Dominance Tests Global Tech Supply Chains



Comments